Wealth Creation: Part 9 & 10 (Double Shot)
Get comfortable with a cup of Joe cause this one can’t be rushed! I will start with a story. To do this, I need to take you back in time to 2007.
As 2007 came to an end, I was the Founder and CEO of a wonderful mid-sized business that I had taken global. Our revenue had grown over 55% per year for eight straight years. Due to our amazing growth, we made the Inc 500 list, which they have since expanded to 5000, coming in somewhere in the low 300’s as one of the fastest growing companies in America.
We were on our way to hitting $12 mm in revenue in just our 8th year in business. We had achieved a very rare feat in business, we had a wait list to die for, with over 10,000 potential customers paying $50 per head simply to apply at a chance of getting chosen to become a customer for one of our 1000 spots per summer.
Imagine this happening in today’s world of competitive online marketing. $500,000 in application fees!
Our company was the world’s largest and most popular summer internship program for college students helping them discover and pursue their dreams while test driving an amazing internship in the world’s most desired cities.
I had founded and bootstrapped the company without any venture funding beyond a few hundred grand in promissory notes. I secured these from friends to help with cash flow from time-to-time due to our tremendous growth. Thanks Mike & Tim. You know who you are!
Given that my company was located in Silicon Valley, the LAND of venture capital, I was proud of the fact that I NEVER took outside money and that my company wasn’t even in technology.
In the two years prior the end of 2007, I took meetings with over 80 Private Equity firms who were considering purchasing my business, turning them all down.
As the global leader in our industry, they thought we could make it to the promised land of $100mm in annual sales with the help of their capital. My company may not have been a Unicorn, but by Silicon Valley standards, it was unique.
We had an amazing company culture. I loved my employees and they loved me back. Three of them actually asked me to officiate their weddings.
One of the employee benefits I created that I am very proud of to this day, was a dream fund to support their dreams. This included matching funds to help them come up with down payments for their first home purchases.
Another one that I adored, took place at Christmas time. I anonymously played a character called Dream Claus awarding vacations around the globe to employees. This character was Santa Claus’s forgotten and bitter older brother. I enjoyed playing the role, throwing daggers at my more popular brother while I gave the more valuable gift of inspiration based travel.
Due to our massive growth, I rewarded my employees with annual pay raises averaging 17%. Given that the national pay raise average during this same time period was less than 3%, you could assume from this that I paid my people very well.
I even took the entire company on annual trips to exotic places like Cancun to grow closer and strategize for each coming year ahead. And they rewarded me with hard work, dedication and loyalty. Only 4 employees left the company in our first nine years.
Personally, I was doing great. I had just married my dream wife Lori. I was making a very good salary of $350,000 per year as the CEO. I drove a very nice car paid for by the company and had a $50,000 expense account which afforded me pretty much any vacation I wanted a couple of times a year as well as meals at wonderful restaurants, turning me into an experienced Foodie!
BUT, even with all this success, when my wife and I found a house that we REALLY loved, and wanted to make our first home together, I learned the harsh reality of what I am going to teach today and possibly help you avoid.
The home we wanted was $1.8 million. Silicon Valley is a lot of things, but cheap it is not! I figured that with my big salary, I would have no problem paying for the mortgage, plus interest rates were at an all time low. The only problem was, I didn’t have the required 20% down payment.
At the time, there were some lenders offering loans WITHOUT down payments, but the terms didn’t make a lot of sense. They were offering something called adjustable rate loans that called for the monthly payments to rise steeply after just three years. This seemed really unattractive to me. I was determined to get a fixed rate loan. A few years later they would make a few Hollywood movies about this era of cheap adjustable rate loans! Sound familiar?
This meant that I needed to come up with $360,000 to meet the 20% down payment requirement. That’s a lot of cheddar! And, what scared me most, is that I didn’t have it all. I had about $260,000, nearly $100k short.
How could this be? I owned and operated a global company. I was the most successful entrepreneur in my orbit of friends and family. I was the guy always taking exotic vacations, driving nice cars, eating at the best restaurants. I was a freaking CEO! How could I NOT have enough money saved for a freaking down payment on a home, something millions of other people owned.
What came next was dread? Who was I going to have to go to, with hat in hand, asking for financial help?
It sure as heck wasn’t going to be my parents. I was the youngest sibling of five and had not asked my parents for money as an adult. I wasn’t going to start now.
I felt weird about going to my Board of Directors to authorize a company loan of this size. Would they look down on me for not saving enough money over the years? I had their respect, and I didn’t want to lose it.
I had a rich Uncle but the second I asked him for a loan, the entire family would hear about it. I had a lot of pride wrapped up in being self-made, totally independent from any family assistance. I didn’t want to give up that invisible badge of honor.
I even went to my commercial bank. They had made many lines of credit available for my company now that we were big enough, so I thought they might help me. You know what they told me – you have no collateral. Your business is doing well, but with no assets, you guys are only as good as your next sales season.
This comment struck a nerve with me, but distracted by my need for $100k, it didn’t really register in its significance.
Feeling a bit helpless and boxed in a corner, the emotions I were feeling were embarrassment, disappointment, frustration and to be perfectly honest, fear. I was scared to realize that owning a global company with $12mm in annual revenue wasn’t enough for a down payment on a house.
I am going to use this story as a teaching moment, as the only reason for telling it was that it was the catalyst for massive change in how I began operating as an entrepreneur from that day forward.
Every entrepreneur I have ever met eventually has a moment like this, where a new desire emerges and they say to themselves these words – “I want to be financially free!”
That story illustrated my moment. And from here on out, this story is going to focus on this desire.
Let’s see if I can convince you to change some behaviors that will lead to more of you keeping your hands raised to these questions.
First, some definitions.
What is a receivable? A receivable is an amount owed to a business in exchange for a product or service. Most entrepreneurs think of this term another way – as SALES! You create a receivable when someone agrees to become a customer and you agree to deliver them your service or product.
Now, if you didn’t know that, it’s ok, because……… you will know the answer to my next question.
Do you know what a liability is?
By definition, a liability is a debt owed from your company to a person or company. In other words, liabilities are debts owed to creditors.
What is an asset?
Business assets are items of value that your business owns, creates or benefits from. Worthy of saying again. Business assets are items of value that your business owns, creates or benefits from. Remember that ending – items of value that your business owns, creates or benefits from.
Assets can range from cash, raw materials and stock, various types of equipment, real estate and intellectual property to name just a few.
Heck, even various forms of Crypto can be a company asset. Heck, Tesla owns 42,902 Bitcoins and these all reside on their Balance Sheet.
And finally, what is equity? Equity is the value attributable to the owners of a business. Please remember this very important term for later.
Now that we ALL know the basics, I am going to teach you how I made the lion’s share of my wealth in less than 7 years. In order to do so, I am going to profile two distinct entrepreneurial strategic paths. Even if you are not an entrepreneur, if you manage your household expenses, this applies to you too!
One path, is a strategy that relies on top line revenue growth and savings from income.
The second path, is an asset strategy of Buy Then Build.
Let’s begin from Day 1 on the Revenue Growth & Savings from Income Approach
Day one, I get a desire to become an Entrepreneur.
I am going to become a…………..wait for it……….a Personal Development Coach.
Knowing that this work is aligned with my purpose and will bring me great joy, I commit to starting a business.
I form my legal entity to become a Personal Development Coach. I decide to develop a service that offers virtual online coaching plus a retreat. The virtual training portion doesn’t cost me much – just my time, fancy computer & camera equipment and the amount Zoom charges for a business account. The retreats however, are expensive!
I plan to run retreats for 8 customers at a time and a total of 4 per year, or one per quarter. I rent retreat compounds in Hawaii and other exotic places that cost my business about $5000 per day to rent.
The retreat lasts 5 nights on average, so that’s $25,000 just for the lodging. Things like private chef meals, alcohol, excursions, entertainment, speakers and staff create another $25,000 in expenses for each retreat for a total cost of $50,000 per retreat. Since I am doing 4 of these a year, my total expenses for retreats is $200,000 with half of that going to lodging.
The next desire I need to focus on is earning a livable wage. Since I lived in California and not Idaho, that is at least $80,000 per year. But I don’t just want to get by. I want to have a good lifestyle so I round up to $10k per month equal to $120,000 annual salary.
And, even though I work from home, keeping my costs down, I need to assume that I will have some additional business expenses costing me another $50,000.
Finally, I want to challenge myself to earn a profit margin around 10%, so I can either reinvest in the company for growth or pay myself a nice fat bonus at the end of every year. Let’s go ahead and pencil in an annual profit bonus of $30,000.
So, to review, to make all these things happen, my total budget is $400,000, and if all goes well, I will be paying myself $150,000 per year. To earn this with 32 total customers (4 retreats x 8 customer per retreat), I divided my projected expenses of $400,000 by 32 to determine my price point of $12,500 per customer. I tell myself, as long as I can offer enough value, I can find the sales!
Emboldened with a price tag that meets all of my needs to do what brings me joy, run great retreats, earn a livable wage and earn an extra 10% profit annually, I start selling.
Sell baby sell!!!!!!!!!!!!!!!
Oh shit, I forgot to factor in marketing costs! Dang, this whole online marketing thing is way harder than I thought. I better pencil in 20% for marketing, so my new budget is $480,000 and I need to charge $15,000 per customer. Budget now completed; I am back to my motto:
Sell baby sell!
After a few months of selling the shit out of my retreats, I get 32 willing customers to agree to my price of $15,000. Woohoo! I crushed It! I’m gonna be rich! Well, let’s play this out over ten years and see if this is true or not.
Try to guess in your head how much the average American saves per year from their net income? Got your guess?
According to the Federal Reserve Bank, over the last 10 years, it has hovered in the 6-9% range. Interesting enough, the average has shot up during the Pandemic to a little over 12%, but that is more a response to consumers not being able to spend like they normally do than better habits forming around saving.
To let this sink in, before COVID struck, the all-time record for savings percentage in a month was 17.3% in May 1975, 45 years ago! It was at the tail end of a recession spurred by rocketing gas prices, government spending on the Vietnam War, and a Wall Street stock crash.
For argument sake though, let’s round up from that 6-9% range for this example and agree on a 10% net savings figure as we did in Part 1 of this Series. After all, you guys are not Average!
The average household in America earns about $78,635 per year in earnings, or around $67,241 after taxes. So my new annual salary of $120,000 is quite a bit better than the national average.
Woohoo, I’m feeling like a Baller!!!!!!!!!!!!!!!
Until tax time at least. Since our country uses a progressive tax system, where the average tax burden increases with income.
Go ahead and take a few seconds to silently guess what your net income will be on annual earnings of $120,000. The total withholding for a $120,000 salary without deductions is $36,198. I can break this down for you all if you need me to.
How does this break down?
Federal Income Tax
- $19,809
State Income Tax
- $6,792
Social Security
- $7,440
Medicare
- $1,740
SDI (State Disability Insurance)
- $31.20
FLI (Family Leave Insurance)
- $385
Total tax
- $36,198
My Net pay would be
* $83,802
That’s a tax rate of 30.2%
So, if the national average of 10% savings applies to me, this means I will have about $8300 in savings left after paying for basic needs, my taxes and my lifestyle from my Baller salary!
BUT, let’s not forget about that 10% profit which calculates to about $30,000 per year. Without anything on the balance sheet to write this profit down though, I have to pay a little over 1/3rd in taxes to Uncle Sam the IRS and my State. This will leave me with a net savings amount of around $20k. Unless, of course, I move to the great state of Florida (wink wink) OR one of the 8 other U.S. states that do not charge an income tax.
In case you are wondering what the other states are, they are Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. And don’t even get me started on Puerto Rico! But let’s stay focused, as this is not a seminar on where to move your business to, although maybe it should be!
Over ten years, if I save every penny of my share of the after-tax profits, I would have $200,000 saved from my annual bonus pay outs. By adding my income savings together with my after-tax profit, my total savings potential is $283,000 after ten years.
By a show of hands, how many of you would take that result if it was guaranteed?
Come on, be honest. Now, let’s introduce some reality into this case study.
Most new businesses take three years on average to turn a profit. So, let’s give YOU………………. OH – what just happened there, are we talking about you now? You thought I was talking about ME didn’t you?
Back to my train of thoughts. Most new businesses take three years on average to turn a profit. So, let’s give YOU a haircut by removing the first three years of your hoped for $20k annual profit distributions. Your new savings are now down to $223,000. And, oh shit, I hate to be the bearer of bad news, but the average lifespan of businesses in the U.S. is about eight and a half years, not 10.
So, let’s assume that you are lucky AND good enough to stay in business for eight and a half glorious years. Well, that means you have to trim the last year and a half from your income AND your after tax profits. And remember, this whole example assumes that you, and I do mean you, are a perfect saver and that no unforeseen expenses of any kind pop up that need YOUR attention.
No medical bills, no car accidents, no speeding tickets, no busted pipes due to a blizzard (a shout out to those of you from Texas), or that crazy sibling that is always asking me for money. None of these things occur for eight and a half years!
And, lets assume you have the discipline to bypass all of your wants and needs like cars, vacations, new clothes, make-up, fun nights out, dates, personal development retreats and anything else that would reduce your savings.
Ahh, that addition was just mean huh?
And those of you listening that have kids, yes, you are correct, your savings balance has now dropped down to zero and you are easily going in the opposite direction paying for tuition, sports, clothes, and everything else raising children requires. Welcome to Debt!
Let’s leave the parent example out though, cause it is not my intention to make everyone on this call depressed nor is it to talk any of you out of becoming Entrepreneurs.
After we do that math though, how much are you left with? Your savings in eight and a half years is approximately $180,550. However, given all the things I just brought into the light, do I have your permission to conservatively round this number down to $150,000? I think I am being nice in stopping there!
At first blush, this might be a LOT more than you might have in your bank account prior to starting your business, but when you divide it by 8.5 years, it comes out to roughly $17,600 saved per year.
Two questions
And feel free answering them to yourself if you agree.
Would you consider yourself wealthy with this amount of savings after ten years?
Would you be satisfied with this amount of net worth after working very hard to build and run a business eight and a half years?
Are you open to learning a different way that would both satisfy you and make you wealthy?
Great, but first I want to address those of you that feel I neglected other possibilities. Maybe you might be thinking, but what if I grow my business Eric, by selling my retreats at a higher price and to more customers.
Or maybe I run more retreats per year. Congratulations if you are thinking this. It means you think like a high achiever. However, before you jump off this call thinking this is all a big waste of your time and to go spend the rest of your day trying to drive more revenue into your business, hear me out.
Let’s use an apples-to-apples comparison to see if we can do BETTER WITHOUT having to actually do better at sales OR grow the business AT ALL! Uwwww, I bet that got your attention Mr. or Mrs. Overachiever!
To do this, we must deploy my first strategy in creating wealth. Let’s examine what this business’s largest non-income expense will be? If you were listening carefully, you heard me say that the lodging for each retreat runs $25,000.
To refresh your memory, this amount was $100,000 of the $480,000 in annual revenue. Wowza – that’s just over 20% of the cost of sales.
Ok, great. We have our focus. Just under 20 cents on the dollar from every dollar of revenue brought into the business goes towards lodging for the retreats. Now, multiply that over 10 years!
If this were your business, you would pay $1,000,000 for my lodging to run 40 retreats. And who would of this hard-earned money go to? Well, the owners of retreat compounds.
Fully grasping this and letting it sink in, in this example - who benefits the most from all your hard work? Me, that’s who!
Please note, that a few minutes ago I went from being the example to you being the example. Why, cause I am the proud owner of not one, but three retreat compounds. All are very valuable assets that bring me substantial income!
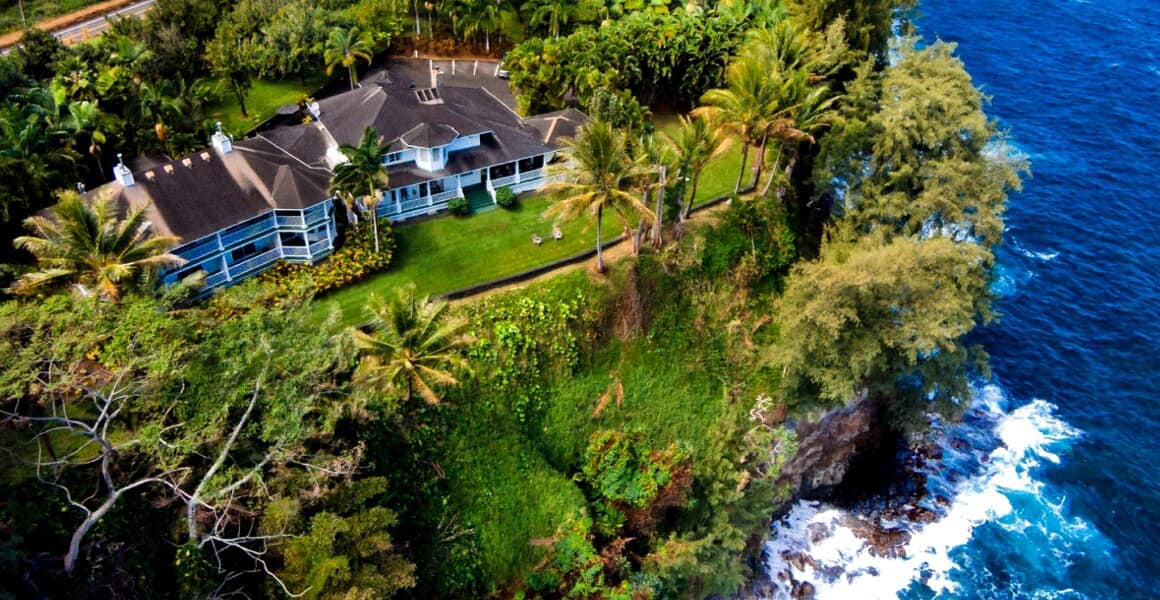
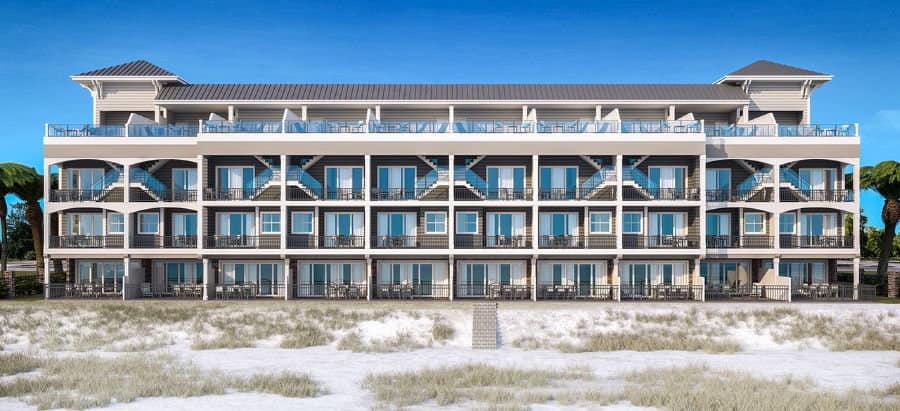
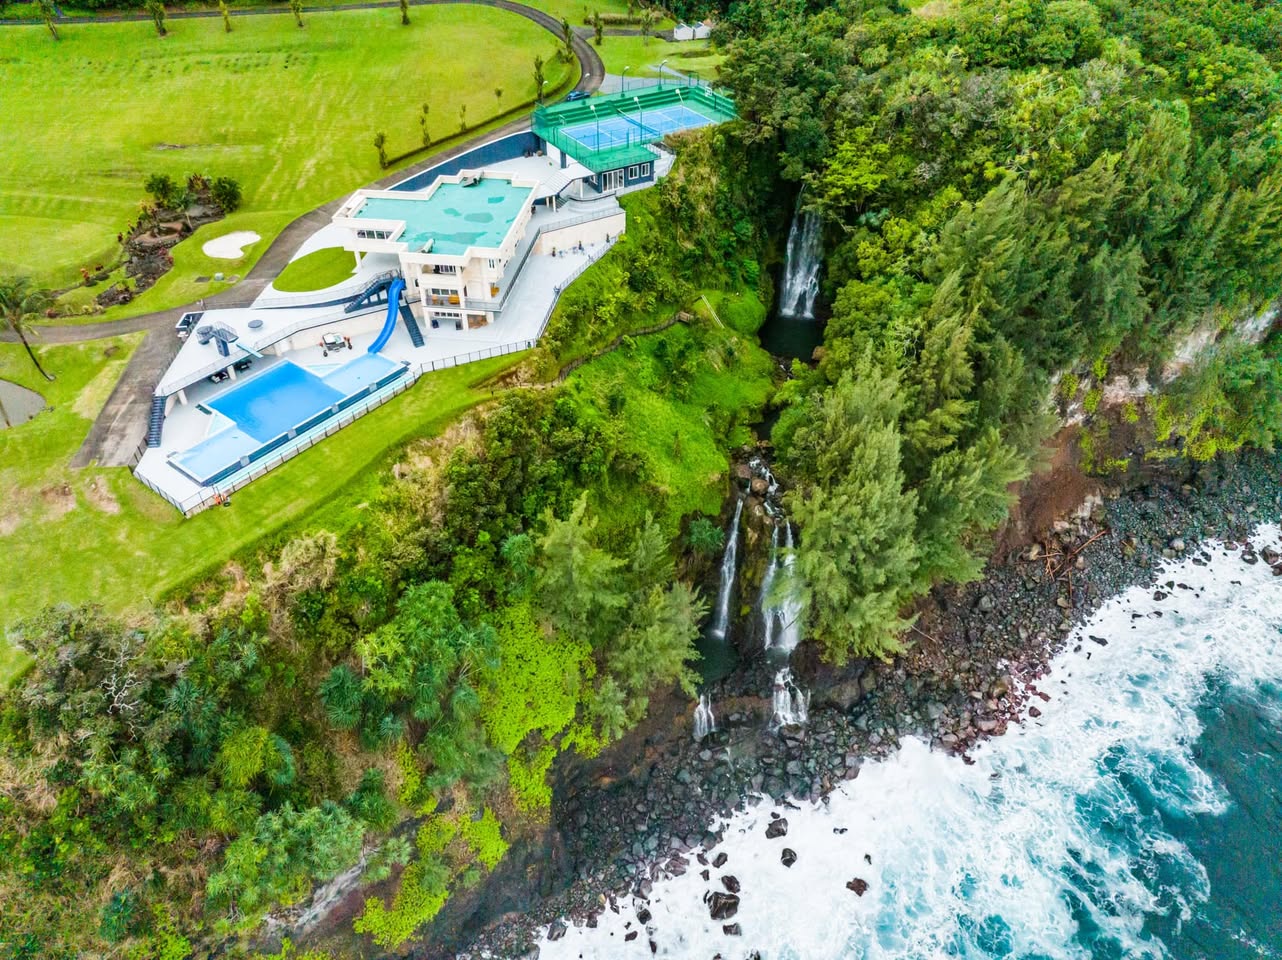
I have Bliss Island in Hawaii, Bliss Beach in Destin, Florida, and now the Waterfalling Estate eight minutes away from my Bliss Island property!
Now, I realize that there are a lot of retreat compounds around the world, but I REALLY want to play the villain in this play, so indulge me and imagine that you book one of my retreat compounds for all ten years.
Well, according to this case study, your business pays me $850,000 for letting you rent my retreat centers for 170 days in ten years. Wowza, that’s $5000 per day!
Shoot, if I earn that from you each year AND I am able to rent just 50% of the other 365 days per year, I would earn a whopping $8.6 million dollars in just eight and a half years. Dangggggggggggg! That’s some real coin!
What if I do it with all three of my retreat compounds? That comes out to $25.8 millions earned in just eight and a half years!Raise your hand if you agree that $25.8 million dollars made in just eight and a half years renting out three awesome retreat compounds that I also get to live in is some pretty satisfying wealth?
I know what you may be thinking. Man, maybe I chose the wrong business to be in? Quickly followed by, but I love being in Personal Development Coach. I get to make an impact and I derive great joy from helping others.
Quickly followed by, I guess I just have to be happy with my $17,600 in wealth generation per year right?
Heck No! Raise your hand if you think this is the choice I make each time I start a new business? Let’s explore what I do instead.
After figuring out the largest expense I will have in a business venture, I make the decision to go shopping to turn my largest expense into an asset BEFORE I even start the business.
Yes, you heard me right. Buy Then Build!
Remember the definition of Business Assets. They are items of value that your business owns, creates or benefits from. I decide to go big cause I really believe in my whole philosophy of using a receivables business to perform against an asset.
Why? because I have enough evidence after building a global receivables only business that grew my top line revenue 55% per year for nine straight years before a global recession slowed me down, leaving me with a life savings of only $260,000, not enough to make a down payment to buy my first freaking home.
Please note that I performed nearly twice as well as the example I just gave banking $30k per year in savings. But, I built a fucking global company that created and then dominated an industry! I wasn’t an average Entrepreneur. I was an exceptional Entrepreneur!
I beat all the odds. My company made it 12 years. I know we have a LOT of great entrepreneurs in this group. Did one of your companies made the INC 500 list, not the 5000 list, which is an awesome accomplishment in today’s age, but The Inc 500? High achievers – do I have your attention now?
Luckily, I learned my lesson by age 40, after 15 years as an entrepreneur, driving a shit tone of revenue and building very little wealth, I learned how to produce a different result without giving up doing what I enjoyed doing for a living. What did I start doing different?
Well, let’s bring this example home. Knowing that lodging will be my biggest non-income expense, I went shopping for a retreat compound that I love. I threw caution to the wind and budgeted $1,000,000 to buy my own retreat compound, cause fuck that old guy making $100,000 a year from me and another $1mm plus from others like me.
You decide(again shifting this back to you instead of me) that you are going be that old before you are old! $1mm dollars!!!! Inconceivable. You say to me, “Idon’t have a million dollars! What the heck are you even talking about Eric?”
Well, let’s take a closer look at whether that statement is 100% true or not. To buy a piece of real estate pretty much anywhere in the world, for residential real estate you need to pay a down payment of roughly 20%, and for commercial property 30%. Let’s use the example of 20%. On a million-dollar asset purchase you would need to pay $200,000 as a down payment so you can finance the rest. But you don’t have two hundred thousand dollars lying around!
Wait a minute, didn’t you just prove to yourself in the example above you’re your receivables only business would spend $1mm in lodging rentals over 10 years? Oh snap, you do have $1 million dollars, you just don’t have it NOW!!!! And besides, you don’t need $1mm right now, you just need $200,000 from someone that wants to be your silent partner in owning the asset.
And what is your sales pitch? That your soon to be asset business already has its first big renter willing to pay it $100,000 per year for ten years. The fact that the renter happens to be your receivables only personal development business is besides the point, cause there will be other renters too! You are simply showing the investor how your asset company will pay off the first million by providing certainty. Oh, every investors favorite word!!!!!!!!!!!!!!
But then FEAR shows up on the scene and declares, what do I know about talking people into giving me money for a great return? ‘Oh WAIT, isn’t that what I do every day generating revenue for me receivables business? you remember. You have to convince 32 people to give you $15k of their hard-earned money to receive my awesome coaching.
Huh, if you can do that, maybe you can raise $200k after all.
This newfound FEAR is bullshit! You know how to do this!
Sell baby sell!
Let’s leap ahead and say you land an investor willing to invest $200,000 for the down payment in return for 20% equity in your $1,000,000 million dollar asset purchase. Newly armed with the needed down payment, you boldly apply for a $800,000 mortgage. Since you have not irreparably harmed your credit score, you get approved at today’s prevailing mortgage interest rate of around 3% (pretend interest rates are normal rather than what they are today). If you plug that into a mortgage calculator on Google, it will tell you that your monthly payments will be roughly $3372 per month.
So, you book an asset on your Balance Sheet for $1,000,000. This includes the down payment PLUS the purchase price of the property. You then list the $200,000 you borrowed from your investor on your Balance Sheet as a liability PLUS the $800,000 you now owe your mortgage lender. Your mortgage lender requires your business to pay your mortgage of $3372 per month. Notice I said your business, not you personally!
The loan stretches you, forcing you to spend all of the $50k you budgeted for business expenses on your annual budget, so you may have to cut back on buying some other shit like pencils and ink cartridges to make it all work. However, only a portion of each payment actually goes towards interest, falling on your Income Statement or P&L. But, a nice big portion goes towards paying down your principal. The principal portion gets applied to your Balance Sheet and reduces the total amount owed to the bank with each payment, turning it into…..wait for it……… EQUITY!!!!!
Remember the definition of equity? - Equity is the value attributable to the owners of a business. Let’s see what your equity would be worth after 8.5 years of mortgage payments. Using an Amortization Schedule you will see that if you made all the mortgage payments you will have paid off $161,047.
This means that your receivables business has contributed to paying off $361,047 of the debt of your asset if you include the $200k down payment. And according to the definition of equity, 80% of this $361,047 asset is legally yours. That’s $288,837
However, a lot has changed in the value of your real estate asset. Over the 8.5 years, it has appreciated, which means it went up in value. Commercial properties typically have an annual return off the purchase price between 6% and 12%. For residential properties it is more like 3% PER YEAR!
But these numbers are very conservative folks, cause they have to take the entire nation into account. And let’s face it, property appreciates much differently depending on the zip code and your choice of property.
But let’s just use 10% annual appreciation as our example. After 8.5 years, your property would become worth $2,250,768. What is your equity of that asset now? Well, 80% of $2,250,768 is $1,800,614.
Now, I realize that you would still owe your investor the original $200,000 plus the rest of the mortgage of $600k ish but even after that, you would net approximately $1million dollars from the sale of this asset.
How crap, you’re a Millionaire!!!!!!!!!!!!!!!
And not just in Company Revenue!!!!!!!!!!!!
My first big asset purchase – the Fox Theatre, did not appreciate only 3% a year or 30% in ten years. It appreciated 200% in 7 years creating $15mm in wealth on a $600,000 initial down payment investment, which I borrowed under this EXACT scenario.
Do you think the investor I borrowed the $600,000 from for the down payment was happy?
She made a $1.2mm return AND got her $600,000 back.
In closing, which option sounds more attractive to you?
The “perfect saver” receivable only based play, which after 10 years, accumulates $17,600 of wealth a year?
Or, investing in an asset that turns your greatest expense into an asset that benefits you, which after 10 years, accumulates a million dollars of wealth?
The best part about this story is that receivables business never even had to grow its top line revenue one dollar to have this result.
Seriously, this means you could keep charging your customers the same price every year and never have to produce more retreats and get more customers, giving yourself the added gift of time freedom on top of financial freedom. You could just do what you love without overworking or over-stressing yourself! You can also buy more properties or more valuable assets and a earn a shit ton more than $1mm. What model builds more wealth?
This is exactly what I did in the past 24 months, using my proven model which has already increased my net worth from that measly $260k ten years ago to over $50 million today. But, I didn’t buy one retreat compound – I bought three!
Working harder is not always the answer my friends. Working smarter in a way that builds incredible wealth doing what you love is my bag. I hope this sparks a curiosity in you to learn to make it yours too!
Feel free to ask questions! I will take the time to answer them!